 BTC
 ETH
 USDT
 BNB
 XRP
 USDC
 SOL
 TRX
 FIGR_HELOC
 ZEC
 HYPE
 DOGE
 XMR
 USDS
 WBT
 LINK
 LEO
 ADA
 NEAR
 XLM
 RAIN
 BCH
 USDE
 DAI
 LTC
 UNI
 CC
 AVAX
 USD1
 SUI
 GRAM
 HBAR
 XAUT
 USDG
 QNT
 PYUSD
 SHIB
 TAO
 ENA
 CRO
 RLUSD
 USYC
 USDY
 OKB
 M
 BUIDL
 AAVE
 BTW
 ONDO
 PUMP
 USDF
 PEPE
 EURSAFO
 PAXG
 ASTER
 USDD
 DOT
 MNT
 WLFI
 WLD
 U
 SKY
 ICP
 HTX
 MORPHO
 BFUSD
 BGB
 USDGO
 VVV
 ETC
 ARB
 JST
 KCS
 GT
 KAS
 POL
 ALGO
 JUP
 RENDER
 ATOM
 PI
 OUSD
 NEXO
 INJ
 LIT
 FIL
 USTB
 AKE
 GHO
 ZRO
 DASH
 CAKE
 XDC
 PEARL
 NIGHT
 ETHFI
 APT
 PYTH
 BDX
 JAAA
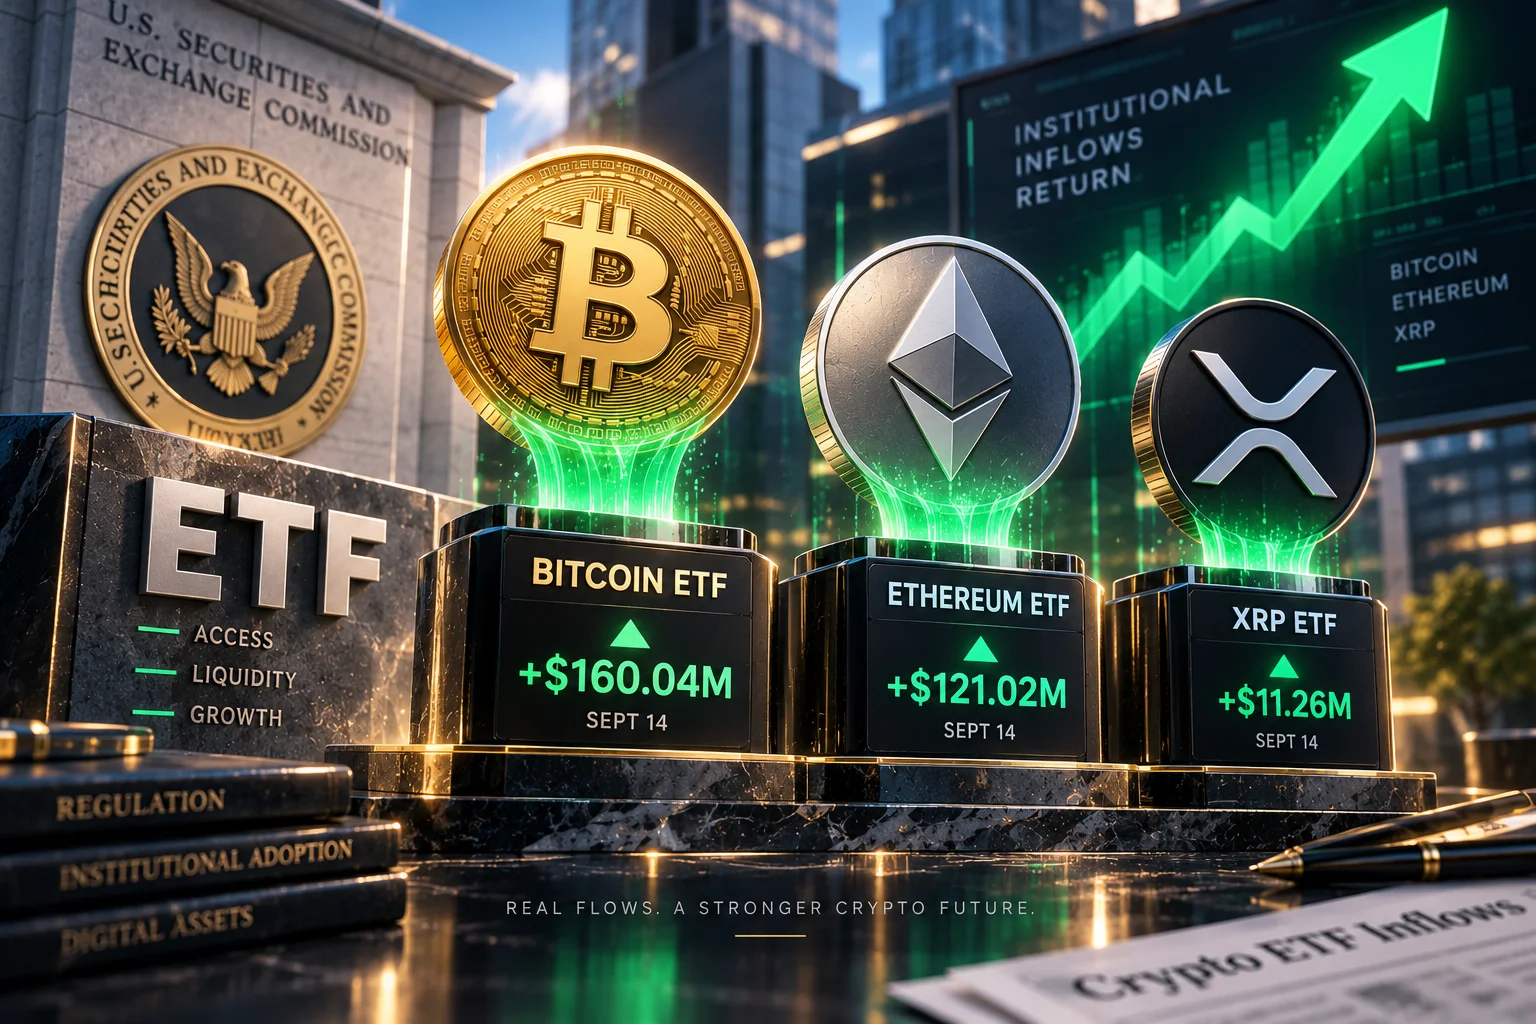
Crypto ETF inflows snapped back on September 14, with bitcoin funds attracting $160.04 million, ether products $121.02 million and XRP funds $11.26 million, according to flow data reported on September 15. But claims that the SEC has just opened in-kind creations across all three assets blur the real story. The watershed order dates to July 29, 2025, and explicitly covered bitcoin and ether ETPs. XRP funds later adopted the same plumbing unevenly. Which products can actually use it-and does an ETF inflow still force a spot-market buy?
For additional context, explore AirdropHotList's crypto market analysis.
The policy is old, but the implementation gap is current
The SEC's July 29, 2025 announcement allowed authorized participants to create and redeem shares of specified crypto exchange-traded products by delivering or receiving the underlying asset instead of cash. The agency said the change could reduce costs and give issuers and market makers greater flexibility.
The associated SEC approval order enumerated bitcoin and ether trusts from issuers including BlackRock, Fidelity, Bitwise, VanEck, Invesco, Franklin Templeton and 21Shares. It did not represent a September 2026 decision covering every crypto fund, nor did it name standalone XRP ETFs that had not yet begun trading.
XRP products subsequently came to market with documents permitting in-kind settlement. That distinction matters: regulatory permission is only the first layer. Authorized-participant agreements, custody arrangements and operational systems determine whether a fund can use the mechanism in practice.
If you want to understand how eligibility, snapshots, claiming, and reward distribution usually work, start with our crypto airdrop guide before joining new campaigns.
In-kind settlement changes the plumbing, not retail ownership
Under a cash creation, an authorized participant sends dollars for a large block of ETF shares. The fund or its designated liquidity provider then purchases the required bitcoin, ether or XRP. A cash redemption reverses the process, potentially requiring the underlying crypto to be sold before dollars are returned.
In-kind settlement removes that compulsory conversion. The authorized participant-or an approved designee-can transfer crypto directly to the trust in exchange for a basket of shares. On redemption, the trust can return the underlying asset instead of selling it.
This can reduce execution costs, slippage and the risk created by timing differences between an ETF order and the corresponding crypto trade. It can also strengthen arbitrage because market makers have another route for correcting premiums or discounts between an ETF's trading price and net asset value.
Retail shareholders do not gain the ability to exchange a few ETF shares for coins in a personal wallet. Creations and redemptions remain institutional basket transactions conducted by authorized participants.
Bitcoin gains efficiency where transaction size is largest
Bitcoin is the clearest scale case. Large creations or redemptions conducted entirely in cash can require liquidity providers to execute substantial spot trades, exposing the process to spreads and short-term price movement. In-kind transfers allow market makers to source bitcoin where liquidity is best, hold inventory and deliver it directly to the trust.
That should make the ETF structure more resilient during high-volume sessions. It does not guarantee lower management fees or higher bitcoin prices, however. The benefit is primarily better execution and a potentially tighter link between ETF shares and the value of the bitcoin backing them.
Not every reward campaign deserves your time. Before you commit, compare this opportunity with our active airdrops list and focus on campaigns with clearer upside, better trust signals, and realistic participation steps.
Ethereum gets the same tool without removing its ETF trade-offs
Ether ETPs received the same regulatory relief in the SEC's 2025 order. An authorized participant can deliver ether rather than forcing an execution agent to purchase it after receiving cash, reducing one layer of trading friction when creations accelerate.
In-kind settlement does not resolve every distinction between holding an ether fund and owning ETH directly. Shareholders still do not control the underlying wallet or interact with decentralized applications through their ETF position. The mechanism improves how the product absorbs and releases inventory; it does not transform the security into on-chain ether.
XRP filings reveal who is actually using in-kind creations
XRP provides the most instructive test because public filings show different operating models inside the same asset category. The Bitwise XRP ETF's August 12 quarterly report recorded $78.724 million of in-kind XRP creations during the first half of 2026, alongside $191.130 million of XRP purchases. It also reported $3.648 million of in-kind redemptions and $30.179 million of XRP sold for redemptions. Bitwise was therefore using a hybrid model rather than merely reserving the right to do so.
The Canary XRP ETF's August 7 filing reported $36.052 million of XRP contributed in-kind during the first half, compared with $52.204 million purchased. No XRP was distributed through in-kind redemptions during that period.
Grayscale shows the other side of the divide. Its August 4 quarterly filing said authorized participants could still submit only cash orders because their agreements did not provide for in-kind creations and redemptions. The fund could be permitted to use the structure while remaining operationally cash-only.
This is the execution gap hidden by the broad "SEC allows in-kind XRP ETFs" framing. Permission is category-level progress; implementation remains product-specific.
Still unsure about wallets, eligibility, or reward rules? Visit our FAQ page for quick answers before joining any new crypto campaign.
The investor paradox: better plumbing can hide spot demand
Analysis: The better crypto ETF plumbing becomes, the less visible its demand may look on exchanges. Under a cash creation, the process normally produces an identifiable purchase of the underlying asset. With an in-kind creation, XRP, bitcoin or ether may move from an authorized participant's existing inventory directly into custody without a matching market buy at that moment.
ETF inflows therefore cannot automatically be translated into same-day spot buying. They still signal demand for fund shares and can place crypto into long-term custody, but their immediate market impact depends on how the authorized participant sourced the inventory. It may have purchased the asset earlier, hedged elsewhere or transferred coins already held.
The counter-case is that cash creations are not inherently dysfunctional. Large liquidity providers can execute efficiently, and some funds may prefer cash because it simplifies participant agreements or operational controls. In-kind capability is an efficiency tool, not proof that one ETF will outperform another.
 Arcus Exchange
 JoinCare
 Breath of Estova
What investors should watch next
- Creation composition: Quarterly filings should show whether crypto entered a trust through direct purchases or in-kind contributions.
- Authorized-participant updates: Cash-only funds moving to hybrid settlement would narrow the execution gap.
- Premiums and discounts: Tighter tracking during large flow days would support the efficiency thesis.
- Spot-market response: Weak price reactions to strong ETF inflows may indicate inventory transfers rather than immediate exchange buying.
Conclusion: the SEC removed a bottleneck, not market risk
The SEC's in-kind shift was a structural upgrade, but it was not a new September 2026 approval simultaneously handed to bitcoin, ether and XRP funds. Bitcoin and ether received the foundational order in July 2025; XRP products later arrived with their own permissions and operating arrangements.
The live story is now execution. Bitwise and Canary have demonstrated that XRP can enter an ETF through in-kind creations, while Grayscale's latest quarterly disclosure showed that regulatory capacity does not automatically produce operational adoption. For crypto investors, the consequence is subtle but important: ETF flows remain valuable demand signals, yet the path from a new share to an on-exchange crypto purchase is no longer one-to-one.
 Gaming Platforms
 Crypto Casinos
 Blockchain Bridges
 Staking & Restaking
 DEX Token Swapping
 Crypto Wallets