 BTC
 ETH
 USDT
 BNB
 XRP
 USDC
 SOL
 TRX
 FIGR_HELOC
 ZEC
 HYPE
 DOGE
 XMR
 USDS
 WBT
 LINK
 LEO
 ADA
 NEAR
 XLM
 RAIN
 BCH
 USDE
 DAI
 LTC
 UNI
 CC
 AVAX
 USD1
 SUI
 GRAM
 HBAR
 XAUT
 QNT
 USDG
 PYUSD
 TAO
 SHIB
 ENA
 CRO
 RLUSD
 USYC
 USDY
 M
 OKB
 BTW
 BUIDL
 AAVE
 ONDO
 PUMP
 USDF
 PEPE
 EURSAFO
 PAXG
 ASTER
 USDD
 DOT
 MNT
 WLFI
 WLD
 SKY
 U
 ICP
 HTX
 MORPHO
 BFUSD
 BGB
 USDGO
 VVV
 ETC
 ARB
 JST
 KCS
 GT
 KAS
 POL
 ALGO
 JUP
 RENDER
 ATOM
 PI
 OUSD
 NEXO
 INJ
 LIT
 FIL
 USTB
 AKE
 GHO
 DASH
 ZRO
 CAKE
 XDC
 PEARL
 ETHFI
 NIGHT
 APT
 PYTH
 BDX
 JAAA
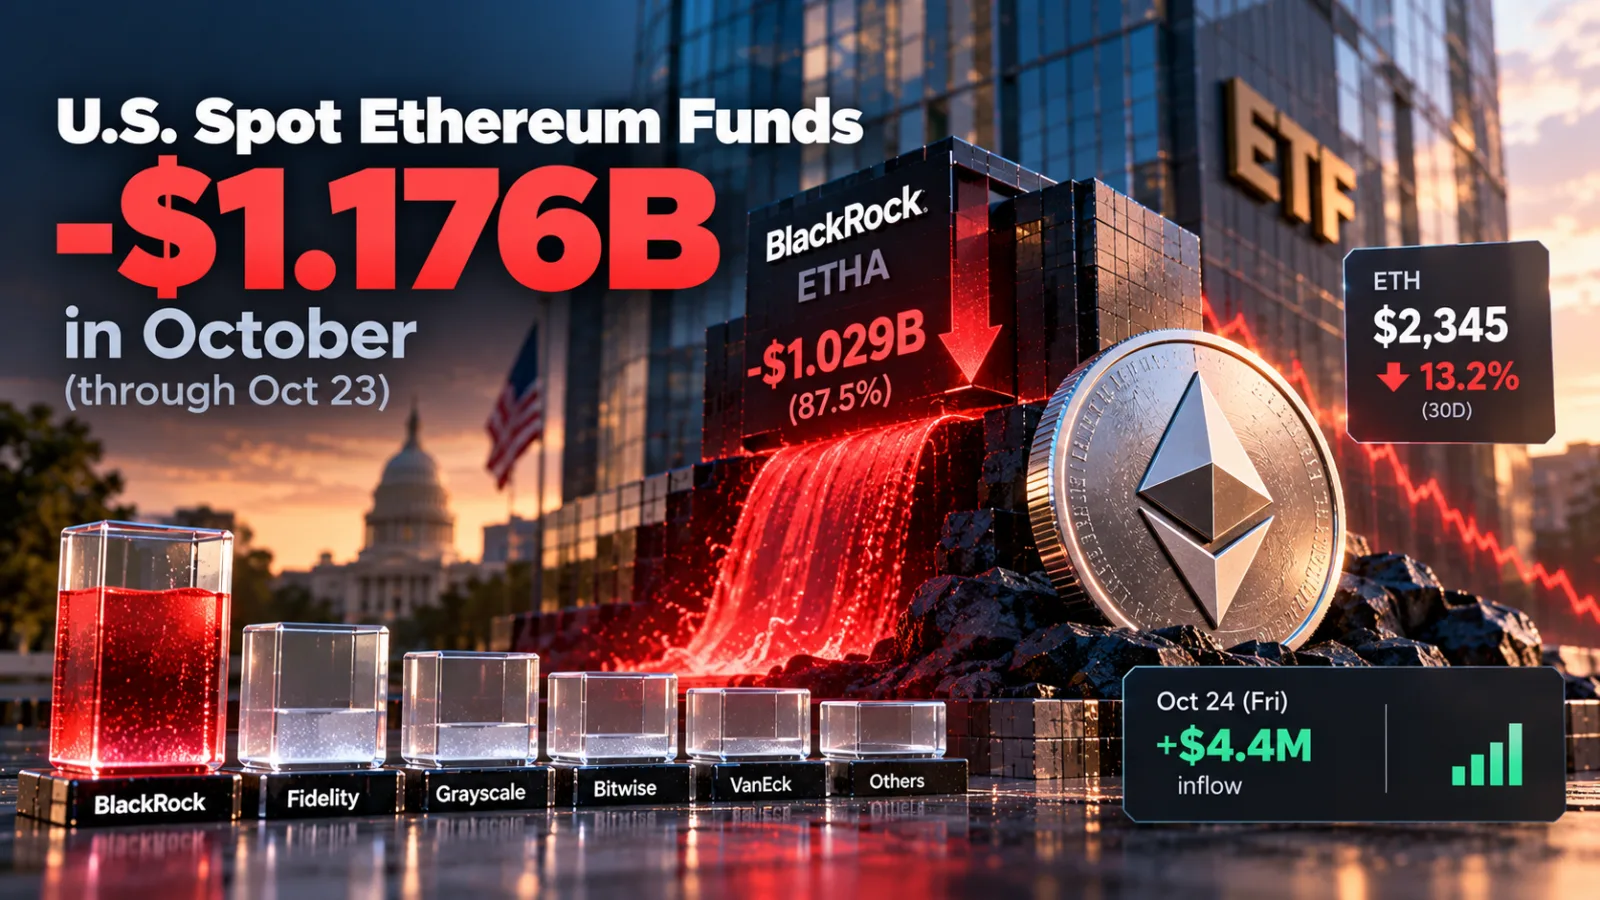
U.S. spot Ethereum funds have lost $1.176 billion in October through October 23, but the headline is less broad than it looks: $1.029 billion, or 87.5%, came from BlackRock's ETHA, according to Farside Investors' daily fund data. ETH trades near $2,345 after falling 13.2% over 30 days, according to CoinGecko, while Friday delivered only a $4.4 million inflow. The real question is whether one dominant redemption channel is close to exhaustion or still gathering force.
For additional context, explore AirdropHotList's crypto market analysis.
The $1.18 billion headline hides a single fund
October's aggregate number looks like a wholesale institutional retreat from Ethereum. The fund-level breakdown is more precise. ETHA generated approximately $1.029 billion of net outflows between October 1 and October 23. Every other product combined lost roughly $146.4 million, while Fidelity's FETH contributed only about $27.1 million of net withdrawals over the period.
That creates an investor paradox: the category-wide signal is decisively bearish, yet participation in the selling is unusually narrow. Concentration can make the headline overstate the breadth of institutional rejection. It can also make the risk more acute because the seller is attached to the largest Ethereum fund. BlackRock reported that ETHA held $7.816 billion in net assets on October 23, far ahead of its competitors.
Official figures also show why falling assets should not automatically be reported as fund outflows. An SEC prospectus supplement put ETHA's net asset value at $9.936 billion on October 5. That figure had fallen by approximately $2.121 billion by October 23, but only about $1.029 billion of the change is captured as October net redemptions. The rest includes the effect of ETH's declining price. Asset shrinkage and investor withdrawals are related, but they are not interchangeable.
DeFi campaigns can involve protocol usage, liquidity, staking, or wallet activity. Before spending gas or locking funds, compare more DeFi airdrops and review the effort-to-reward balance.
ETHA's reverse split did not create the redemption wave
The largest daily move deserves particular scrutiny. ETHA recorded a $201.9 million outflow on October 6, the same day its one-for-three reverse split took effect. That timing could invite the conclusion that the corporate action distorted the flow data.
The official filing says otherwise. BlackRock's SEC supplement states that the split proportionately reduced shares outstanding and increased net asset value per share, but did not change the trust's aggregate asset value, apart from cash paid for fractional interests. The split therefore makes raw share-count comparisons before and after October 6 misleading, but it cannot by itself explain a $201.9 million redemption estimate.
Dollar-denominated creation and redemption data are the cleaner signal. ETHA then posted further outflows of $116.1 million on October 7, $109.8 million on October 14 and $95.4 million on October 19. The selling did not disappear once the split was complete.
If this opportunity involves trading, deposits, or exchange activity, review our crypto trading guide for beginners to understand fees, risk control, and safer decision-making.
ETF outflows matter without equaling instant exchange sales
There is another distinction traders should preserve. A dollar of ETF outflow is not necessarily a dollar of ETH immediately sold on a public exchange. BlackRock's ETHA prospectus allows baskets to be redeemed for either cash or ether. A cash redemption may require the trust to sell ETH, while an in-kind redemption transfers ether to an authorized participant or its designated account.
Either route removes demand from the ETF wrapper, but the immediate market impact can differ. In-kind redemptions move ETH out of the trust without proving that the recipient sold it. Cash redemptions have a more direct sale mechanism. Aggregate flow data reveal the direction of investor demand, not the final destination of every redeemed coin.
The price response nevertheless shows that other buyers have not fully absorbed the withdrawal. CoinGecko placed ETH near $2,345 on October 25, with the token down 13.2% over 30 days and worth roughly 0.0291 BTC. Weakness against both the dollar and Bitcoin makes the ETF outflow story harder to dismiss as an isolated portfolio adjustment.
Friday's $4.4 million inflow does not yet change that reading. It recovered less than 0.4% of October's net withdrawal and came from Fidelity's FETH and Morgan Stanley's MSSE, while ETHA registered no inflow. One positive session can interrupt the pattern without reversing it.
If you want reward-focused opportunities that involve tasks or activity, compare more earn crypto airdrops before choosing where to spend your time.
Staking products complicate the institutional demand signal
Ethereum's ETF market is also becoming less homogeneous. Some products now offer exposure to staking rewards, while ETHA remains a straightforward spot-price vehicle. Fidelity says FETH stakes ether and distributes resulting rewards quarterly, subject to fees and staking risks.
That product divergence creates a plausible counter-case to the bearish interpretation. Investors could reduce a non-staking position while seeking a yield-bearing Ethereum wrapper elsewhere. If that rotation were occurring at scale, ETHA could remain weak without signaling equivalent rejection of ETH itself.
October's numbers do not yet confirm that defense. FETH remained modestly negative for the month, and inflows into other funds were far too small to offset ETHA's withdrawals. The possibility of rotation matters, but observable demand is still missing.
 Arcus Exchange
 JoinCare
 Breath of Estova
Three paths now define Ethereum's setup
In the bullish path, ETHA stops posting large redemptions and aggregate inflows broaden across several issuers. A sustained ETH/BTC recovery above 0.03 would strengthen the case that the market has absorbed October's supply and that institutional demand is returning rather than merely stabilizing.
The base case is less dramatic: ETHA outflows slow, smaller funds alternate between modest inflows and withdrawals, and Ethereum trades with the wider crypto market without gaining relative strength. That would remove one source of pressure but would not provide the persistent marginal buying needed for a durable repricing.
The bearish path requires no complicated technical pattern. Another sequence of $100 million-plus ETHA redemptions, combined with ETH/BTC remaining below 0.029, would show that the largest institutional access channel is still distributing into insufficient demand. Because October's selling is concentrated, one large ETHA print now carries more information than several small inflows elsewhere.
Conclusion
The clean reading is neither that Wall Street has abandoned Ethereum nor that October's ETF losses are harmless bookkeeping. The market has experienced a real $1.176 billion withdrawal from its U.S. spot fund complex, overwhelmingly driven by BlackRock's ETHA, while ETH has underperformed Bitcoin. Concentration is the reason the trend could reverse quickly, but it is also why the latest $4.4 million inflow proves very little.
The next confirmation will come from four observable signals:
- Whether ETHA can complete a full trading week without net redemptions.
- Whether positive flows broaden beyond one or two smaller products.
- Whether ETH/BTC reclaims 0.03 or loses the 0.029 area decisively.
- How much of the $1.176 billion October deficit is recovered, rather than merely interrupted by isolated inflow days.
Until ETHA stops dominating the exit column, Ethereum's ETF problem remains less about the number of sellers than the size of the door they are using.
 Gaming Platforms
 Crypto Casinos
 Blockchain Bridges
 Staking & Restaking
 DEX Token Swapping
 Crypto Wallets