 BTC
 ETH
 USDT
 BNB
 XRP
 USDC
 SOL
 TRX
 FIGR_HELOC
 ZEC
 HYPE
 DOGE
 XMR
 USDS
 WBT
 LINK
 LEO
 ADA
 NEAR
 XLM
 RAIN
 BCH
 USDE
 DAI
 LTC
 UNI
 CC
 AVAX
 USD1
 SUI
 GRAM
 HBAR
 XAUT
 USDG
 QNT
 PYUSD
 SHIB
 TAO
 ENA
 CRO
 RLUSD
 USYC
 USDY
 OKB
 M
 BUIDL
 AAVE
 BTW
 ONDO
 PUMP
 USDF
 PEPE
 EURSAFO
 PAXG
 ASTER
 USDD
 DOT
 MNT
 WLFI
 WLD
 U
 SKY
 ICP
 HTX
 MORPHO
 BFUSD
 BGB
 USDGO
 VVV
 ETC
 ARB
 JST
 KCS
 GT
 KAS
 POL
 ALGO
 JUP
 RENDER
 ATOM
 PI
 OUSD
 NEXO
 INJ
 LIT
 FIL
 USTB
 AKE
 GHO
 ZRO
 DASH
 CAKE
 XDC
 PEARL
 NIGHT
 ETHFI
 APT
 PYTH
 BDX
 JAAA
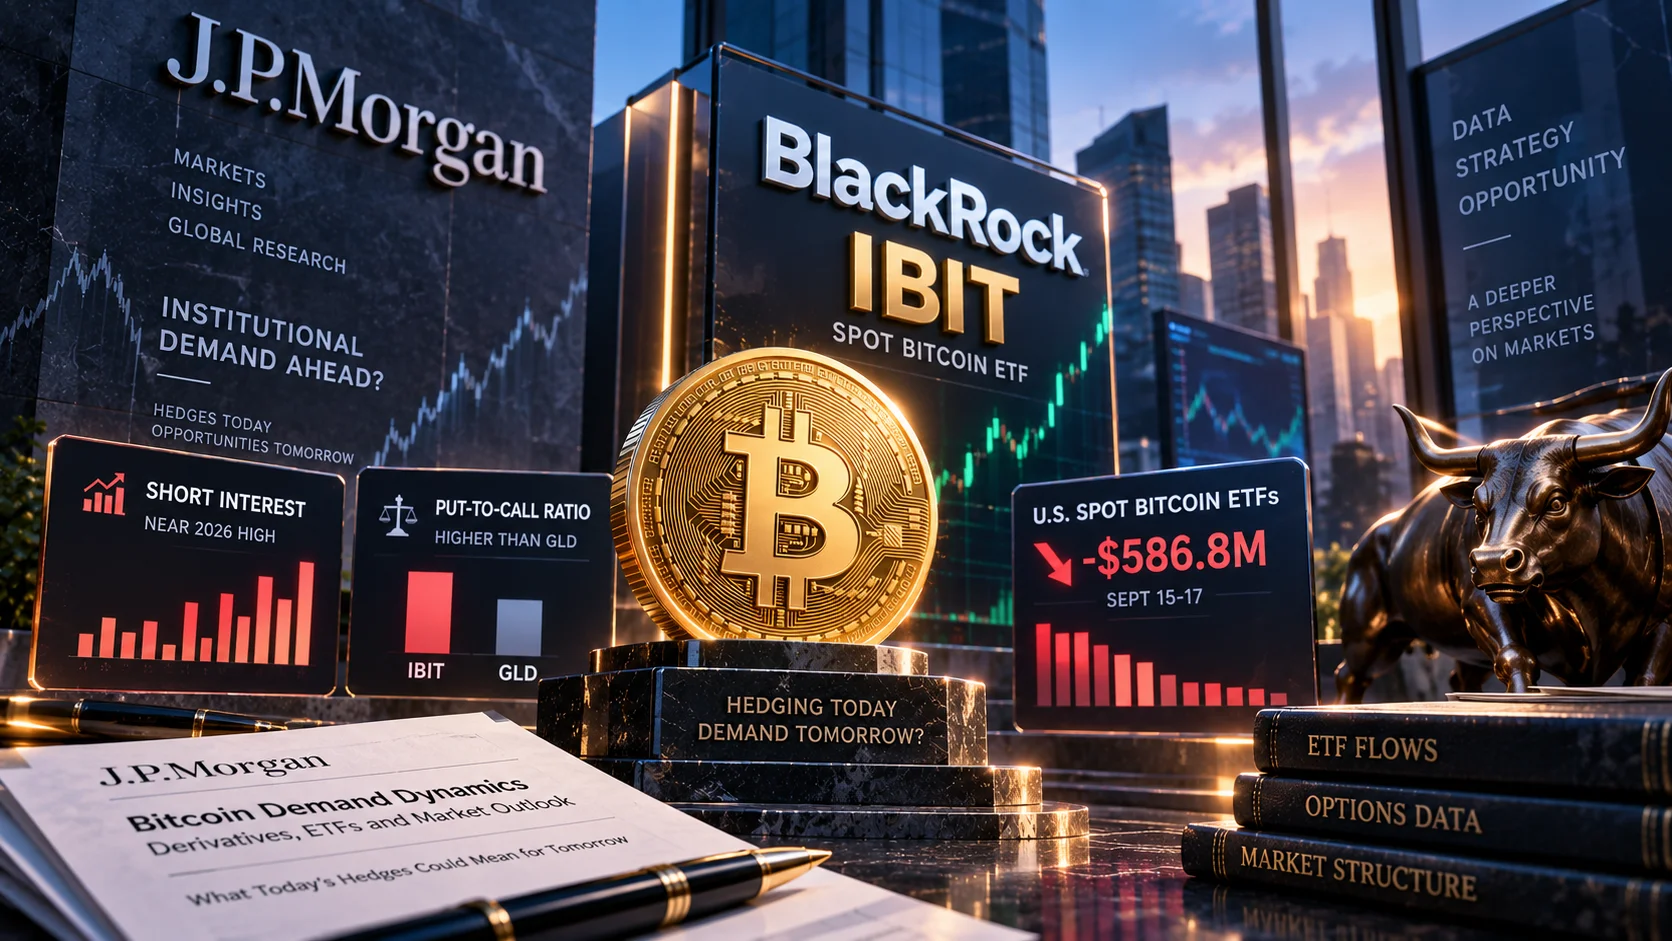
JPMorgan has identified an unusual source of potential Bitcoin demand: the defensive positions built around BlackRock's IBIT. In a September 16 report, analysts said IBIT short interest was near its 2026 high and its put-to-call open-interest ratio exceeded gold ETF GLD's, creating possible support if those hedges unwind. The catch is in the cash data: U.S. spot Bitcoin ETFs remained down $586.8 million across September 15-17, even after Thursday's rebound. Is that caution becoming fuel-or still flashing a warning?
For additional context, explore AirdropHotList's crypto market analysis.
JPMorgan's "skepticism premium" is the real signal
The bank's argument, reported by The Block, is more nuanced than a straightforward prediction of new institutional buying. JPMorgan's analysts, led by Nikolaos Panigirtzoglou, said both Bitcoin and gold ETFs received inflows after late July, but gold funds had recovered all of their earlier 2026 outflows while Bitcoin funds had recovered only about half.
The more important divergence appeared in derivatives and short positioning. According to the bank, short interest in BlackRock's iShares Bitcoin Trust ETF remained close to its highest level of 2026, while short interest in SPDR Gold Shares was below its historical average. IBIT also carried a higher put-to-call open-interest ratio than GLD, which JPMorgan interpreted as evidence of heavier Bitcoin hedging.
That produces the central investor paradox: the asset facing more skepticism can have more latent buying power if the skepticism fades. Short sellers may need to repurchase IBIT shares, protective options may be closed, and investors who delayed allocations may return. Yet defensive positioning is not bullish by itself. Without a catalyst that changes risk perception, it can simply reflect expectations of further volatility or redemptions.
If you want reward-focused opportunities that involve tasks or activity, compare more earn crypto airdrops before choosing where to spend your time.
Why an IBIT hedge unwind could reach the spot Bitcoin market
IBIT is large enough for changes in its positioning to matter beyond one Nasdaq-listed product. BlackRock reported approximately $59.4 billion in IBIT net assets as of September 16. Its scale, liquidity and active options market have made it a primary venue for institutions seeking regulated Bitcoin exposure, relative-value trades or portfolio protection.
A reduction in IBIT hedging can affect Bitcoin through three connected channels. Investors closing outright short positions must buy ETF shares back. A change in options exposure can require dealers to rebalance their IBIT hedges, although the direction and magnitude depend on the dealers' underlying books. Most importantly, sustained net ETF creations require the trust structure to absorb additional Bitcoin exposure, converting improved investor demand into a spot-market consequence.
None of those mechanisms guarantees a rally. Some IBIT shorts may be paired with long Bitcoin or futures positions rather than expressing a bearish view. Puts may protect profitable long-term holdings, and closing them does not automatically create spot buying. JPMorgan's thesis therefore needs two developments at once: declining defensive positioning and improving net creations. One without the other is weak confirmation.
The latest ETF flows only partly confirm the reversal
The most recent completed flow data show why investors should not treat JPMorgan's observation as a finished catalyst. U.S. spot Bitcoin ETFs recorded $450.4 million of net outflows on September 15 and another $295.9 million on September 16. Flows reversed to a $159.5 million inflow on September 17, leaving the three-session balance negative by $586.8 million.
BlackRock's fund supplied more than the entire September 17 category rebound: IBIT attracted $183.7 million, while Fidelity's FBTC lost $16.6 million and VanEck's HODL lost $7.6 million. That concentration is constructive for the specific IBIT unwind thesis, but it is less convincing as proof of broad institutional demand. A durable reversal would normally show positive participation across several major issuers rather than dependence on one fund.
The regulatory backdrop also gives cautious investors a reason to keep protection in place. On September 15, the U.S. Senate failed to invoke cloture on the motion to proceed with the CLARITY Act in a 49-50 vote, short of the 60 votes required. The vote coincided with the largest ETF withdrawal of the three-session period, although timing alone does not prove that the legislative defeat caused the redemptions.
For JPMorgan's setup, the distinction matters. Better crypto-policy news could persuade institutions to reduce protection and rebuild exposure. Continued legislative uncertainty could instead preserve the same elevated hedging that the bank sees as potential fuel.
If this opportunity involves trading, deposits, or exchange activity, review our crypto trading guide for beginners to understand fees, risk control, and safer decision-making.
The $1.85 trillion headline is not a JPMorgan target
A separate long-term Bitcoin ETF projection circulating alongside JPMorgan's report needs careful labeling. Bloomberg senior ETF analyst Eric Balchunas argued on September 17 that Bitcoin ETFs could eventually hold three times the assets of gold ETFs, citing Bitcoin's younger investor base, the prospect of greater institutional adoption as volatility matures, and a stronger distribution network.
The widely repeated $1.85 trillion figure is scenario math built from that view-not a JPMorgan forecast and not a Bitcoin price target. The World Gold Council reported $615 billion of global gold ETF assets at the end of August 2026; multiplying that snapshot by three produces approximately $1.845 trillion.
ETF assets can increase through both net inflows and appreciation in the underlying asset. Consequently, a future Bitcoin ETF asset total cannot be translated into a reliable BTC price by simple division unless assumptions are also made about fund holdings, Bitcoin supply and future gold ETF growth. Balchunas's argument is a structural adoption thesis. JPMorgan's is a near-term positioning thesis. Combining them into one purported bank target would be inaccurate.
Bull, base and bear cases for the hedge-unwind setup
If you want to understand how eligibility, snapshots, claiming, and reward distribution usually work, start with our crypto airdrop guide before joining new campaigns.
Bull case: defensive positioning becomes forced demand
IBIT and the wider ETF group produce several consecutive sessions of broad net inflows while IBIT short interest and relative put demand decline. That combination would suggest investors are not merely trading a one-day rebound; they are removing protection and adding exposure. Short covering and dealer rebalancing could then amplify the underlying demand.
Base case: IBIT improves, but the category remains divided
BlackRock continues attracting allocations while other large funds alternate between modest inflows and redemptions. Hedging remains elevated because institutions want Bitcoin exposure without accepting its full downside volatility. Under this outcome, the "skepticism premium" persists but does not become a decisive catalyst.
 Arcus Exchange
 JoinCare
 Breath of Estova
Bear case: hedges were warning about more redemptions
Multi-fund outflows resume, put demand rises and IBIT's short interest remains elevated or increases. That would indicate defensive positioning was anticipating weaker demand rather than storing future buying power. Further regulatory setbacks could strengthen this outcome by delaying allocations from institutions waiting for clearer U.S. market rules.
Conclusion: skepticism is fuel only after it starts burning
JPMorgan has identified a credible asymmetry, not issued an all-clear. Bitcoin carries heavier ETF hedging than gold, so an improvement in sentiment could release more marginal demand. The September 17 IBIT inflow is an early positive signal, but the wider category's three-session deficit shows that confirmation is still missing.
- ETF breadth: Watch whether IBIT, FBTC and ARKB turn positive together rather than relying on one fund.
- Positioning: Look for IBIT short interest and put-to-call open interest to decline as cash inflows improve.
- Flow persistence: Several positive sessions would matter more than one large daily creation.
- U.S. policy: A renewed path for the CLARITY Act-or replacement legislation-could remove a reason to maintain hedges.
Positive, broad ETF flows combined with falling defensive positioning would confirm JPMorgan's thesis. Renewed redemptions accompanied by heavier hedging would invalidate it. Until one of those combinations appears, IBIT's crowded protection is best viewed as stored potential energy-not realized Bitcoin demand.
 Gaming Platforms
 Crypto Casinos
 Blockchain Bridges
 Staking & Restaking
 DEX Token Swapping
 Crypto Wallets