 BTC
 ETH
 USDT
 BNB
 XRP
 USDC
 SOL
 TRX
 FIGR_HELOC
 ZEC
 HYPE
 DOGE
 XMR
 USDS
 WBT
 LINK
 LEO
 ADA
 NEAR
 XLM
 RAIN
 BCH
 USDE
 DAI
 LTC
 UNI
 CC
 AVAX
 USD1
 SUI
 GRAM
 HBAR
 XAUT
 USDG
 QNT
 PYUSD
 SHIB
 TAO
 ENA
 CRO
 RLUSD
 USYC
 USDY
 OKB
 M
 BUIDL
 AAVE
 BTW
 ONDO
 PUMP
 USDF
 PEPE
 EURSAFO
 PAXG
 ASTER
 USDD
 DOT
 MNT
 WLFI
 WLD
 U
 SKY
 ICP
 HTX
 MORPHO
 BFUSD
 BGB
 USDGO
 VVV
 ETC
 ARB
 JST
 KCS
 GT
 KAS
 POL
 ALGO
 JUP
 RENDER
 ATOM
 PI
 OUSD
 NEXO
 INJ
 LIT
 FIL
 USTB
 AKE
 GHO
 ZRO
 DASH
 CAKE
 XDC
 PEARL
 NIGHT
 ETHFI
 APT
 PYTH
 BDX
 JAAA
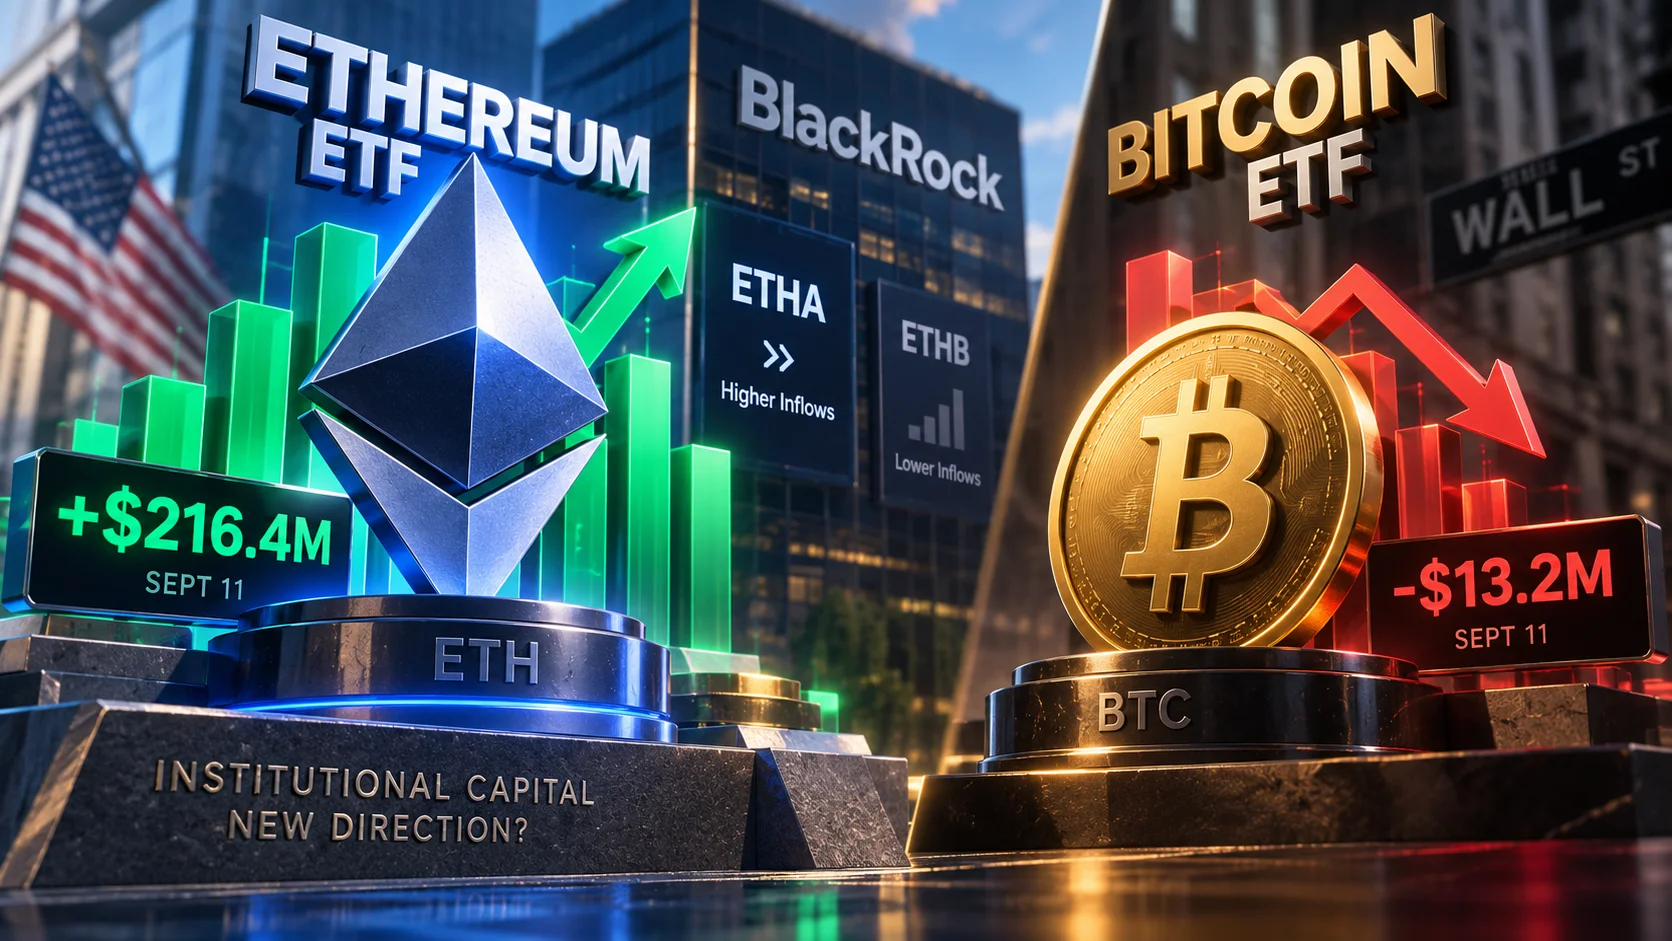
U.S. spot Ether ETFs pulled in $216.4 million on Friday, September 11, while Bitcoin ETFs lost $13.2 million for a fourth consecutive session, according to Farside Investors' Ether data and its Bitcoin flow table. The split flipped Ether funds to a positive $196.9 million week as Bitcoin products shed $462.7 million. Yet the critical detail was inside BlackRock's shelf: plain-vanilla ETHA absorbed far more than yield-bearing ETHB. Is institutional capital rotating into Ethereum, or simply choosing the most liquid wrapper before staking economics fully matter?
For additional context, explore AirdropHotList's crypto market analysis.
Friday erased Ether's red week in one session
The Ether ETF complex had struggled to establish momentum during the holiday-shortened week. Funds lost $24.3 million on September 8, added $34.7 million the following day and surrendered $29.9 million on September 10. Friday's $216.4 million intake did more than offset those moves, leaving the four-session total at approximately $196.9 million, based on Farside's daily fund-level figures.
Bitcoin delivered the inverse pattern. Its U.S. spot products posted net outflows of $46.6 million, $120.2 million, $282.7 million and $13.2 million across the same four sessions. That $462.7 million weekly loss reversed nearly 47% of the roughly $986.7 million the funds had collected during the previous week, including August 31, according to calculations from Farside's Bitcoin ETF table.
This was therefore not just another positive Ether flow day. Capital moved toward ETH exposure precisely as the larger Bitcoin ETF category remained under redemption pressure. The contrast matters because simultaneous inflows would signal broad crypto risk appetite; opposing flows are more consistent with selective allocation or rotation.
Still unsure about wallets, eligibility, or reward rules? Visit our FAQ page for quick answers before joining any new crypto campaign.
BlackRock won the flow race, but ETHB did not
BlackRock's two Ether products generated $167.1 million, or about 77% of Friday's total, according to Farside. However, the distribution was lopsided: ETHA attracted $148.8 million, almost 69% of all Ether ETF inflows, while the newer staked product ETHB added $18.3 million, equivalent to roughly 8.5%.
That gap challenges the simplest explanation for Ethereum's ETF advantage. If investors were buying primarily for native yield, ETHB should have captured a much larger share. Instead, the market favored BlackRock's older, non-staking product, suggesting that liquidity, familiarity and execution depth still outrank incremental staking income for many large allocators.
The official fund data supports that interpretation. BlackRock reported ETHA net assets of $8.96 billion and September 11 trading volume of 97.2 million shares. Its ETHB page showed $1.05 billion in assets and volume of 1.89 million shares on the same date. ETHA was roughly 8.5 times larger by assets and traded about 51 times as many shares that day. Those differences can materially affect spreads, market impact and the ease of entering or exiting a large position.
Other issuers still participated. Farside recorded $29.1 million for Bitwise's ETHW, $11.4 million for Fidelity's FETH, $5.1 million for Grayscale's lower-fee ETH product and $3.7 million for VanEck's ETHV. The session was concentrated, but it was not exclusively a one-fund creation event.
If you prefer curated opportunities instead of browsing everything manually, check our featured airdrops and compare higher-signal campaigns first.
Staking changes the wrapper-not Ethereum's underlying risk
ETHB remains strategically important even though it lagged ETHA on Friday. BlackRock describes the fund as seeking exposure to both Ether's price and rewards earned by staking part of its holdings. As of September 11, its 30-day staking rewards rate was 1.52%, and the product was structured to make monthly distributions.
That creates a proposition Bitcoin cannot replicate at the protocol level. A Bitcoin ETF offers price exposure, minus costs. A staking-enabled Ether ETF can combine price exposure with protocol-generated rewards, giving traditional accounts access to an economic feature that previously required direct custody, an exchange staking service or on-chain validator infrastructure.
The investor paradox is that Ethereum becomes easier to own by hiding its on-chain complexity, but the extra return depends on accepting more of that complexity inside the fund. BlackRock's ETHB prospectus states that the sponsor intends to stake 70% to 95% of the trust's Ether under normal market conditions. It also identifies variable activation and exit periods, validator penalties and slashing as risks.
Persistent ETHB creations could place more fund-held Ether into staking and reduce the portion immediately available for sale. That is not a permanent supply lock: redemptions, distributions and liquidity management can reverse the effect. Still, the mechanism creates a more explicit bridge between ETF demand, Ethereum's validator economy and liquid ETH supply than exists for Bitcoin funds.
If you want to understand how eligibility, snapshots, claiming, and reward distribution usually work, start with our crypto airdrop guide before joining new campaigns.
Bitcoin's outflows make the divergence harder to dismiss
Friday's Bitcoin outflow was modest compared with Thursday's $282.7 million loss, but it extended the red streak. BlackRock's IBIT shed $19.2 million, while VanEck's HODL and Morgan Stanley's MSBT collected $2.2 million and $3.8 million respectively, according to Farside. The largest Bitcoin vehicle was therefore losing money as BlackRock's Ether products were taking it in.
That does not prove investors sold Bitcoin ETFs to buy Ether ETFs. Daily fund data cannot identify whether the same accounts executed both sides. It does show that institutional wrappers were transmitting opposite demand signals for the two largest crypto assets during the same session.
 Arcus Exchange
 JoinCare
 Breath of Estova
The rotation case still needs confirmation
Price action offered an initial confirmation. Ether gained roughly 2.5% against Bitcoin on September 11, while its BTC-denominated value had risen about 34% over the preceding month, according to CoinGecko's ETH/BTC history. ETF allocation and relative performance were therefore pointing in the same direction.
One session, however, cannot establish a durable institutional rotation. Friday's inflow could represent a large model-portfolio rebalance, delayed creations or investors buying after weakness rather than expressing a long-term preference for Ethereum. The dominance of ETHA also suggests the immediate trade was primarily about liquid ETH exposure, not a wholesale repricing of staking yield.
Conclusion: watch whether yield or liquidity wins
The defensible conclusion is narrower than "institutions have chosen Ethereum." Ether ETFs decisively outperformed Bitcoin funds for one important session and finished the week positive, while ETH/BTC strengthened. Yet BlackRock's liquid, non-staking ETHA-not its yield-bearing ETHB-captured most of the demand. The next flow sequence will reveal whether staking expands the buyer base or remains secondary to liquidity.
- Flow persistence: Two or more additional positive Ether ETF sessions would strengthen the rotation case; an immediate reversal would weaken it.
- ETHB participation: A sustained increase from its 8.5% share of Friday's inflow would indicate that staking yield is becoming a material allocation driver.
- ETH/BTC: Holding near or above the recent 0.0325 area would confirm relative strength. A retreat toward early September's 0.0313 region would undermine the signal.
- Bitcoin redemptions: Continued BTC ETF outflows alongside positive ETH flows would support selective rotation. Renewed Bitcoin inflows coupled with weaker Ether demand would favor the one-day-rebalance explanation.
 Gaming Platforms
 Crypto Casinos
 Blockchain Bridges
 Staking & Restaking
 DEX Token Swapping
 Crypto Wallets